Image from Pexels
What would it take for you to feel genuinely secure about your financial future? Whether you’re in your twenties starting your first job or in your fifties reassessing your retirement strategy, the answer lies in building a solid financial foundation. Many people delay taking control of their money, thinking they’ll address it when circumstances feel “right” or when they have more income. The truth is that financial security doesn’t depend primarily on your age or current salary. Instead, it rests on understanding core principles and implementing them consistently, regardless of where you are in life.
1. Assess Your Current Financial Position
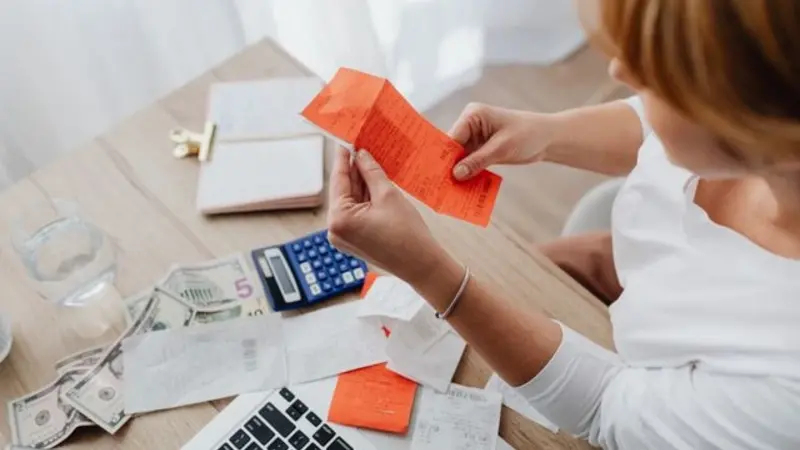
Before you can build anything, you need to know exactly what you’re working with. Take time to gather information about all your financial accounts, including savings, checking, investments, and retirement plans. Write down or document all your debts as well, from credit cards to student loans to mortgages. Calculate your total monthly income from all sources and list every monthly expense you have. This comprehensive picture helps you understand your cash flow and identify areas where money goes without adding real value to your life.
Being honest with yourself during this assessment is critical. Many people discover they spend far more on subscriptions, dining out, or impulse purchases than they realized. The goal is not to judge yourself but to gather accurate information. You might use budgeting apps or simple spreadsheets to organize this data, whichever system feels most manageable. Once you have this baseline, you can make informed decisions about where to direct your financial efforts. This assessment serves as your starting point and the benchmark against which you’ll measure future progress.
2. Create a Realistic Budget That Works for Your Lifestyle
A budget is not meant to feel restrictive or punishing. Instead, think of it as a spending plan that aligns your money with your actual priorities and values. Start by categorizing your expenses into fixed costs (rent, insurance, loan payments) and variable costs (groceries, entertainment, transportation). Then honestly assess which variable expenses bring genuine satisfaction and which ones you could reduce without meaningfully affecting your quality of life. The key is building a budget you can actually follow rather than creating an overly austere plan that you’ll abandon within weeks.
Many financial advisors recommend allocating money using percentage-based frameworks, though the exact percentages matter less than the principle. The core idea is that you allocate money to necessities, debt repayment, savings, and discretionary spending in a way that feels sustainable. Your budget should have flexibility built in because life includes unexpected expenses and changing circumstances. Review your budget monthly at first and adjust it as needed based on what you learn about your actual spending patterns. As you gain confidence, you might review it quarterly or adjust only when circumstances change significantly.
3. Build and Maintain an Emergency Fund
Financial emergencies happen regardless of age or income level. A car breaks down, a medical situation arises, or work hours get cut unexpectedly. Without an emergency fund, these events force people to rely on credit cards or loans at a time when they can least afford to take on debt. An emergency fund is simply money set aside specifically for unexpected expenses, kept in an accessible but separate account so you do not accidentally spend it. This fund serves as a buffer that protects your other financial goals and prevents a crisis from derailing your progress.
Financial professionals generally recommend saving three to six months of basic living expenses in your emergency fund. If six months feels overwhelming, start smaller. Begin with a thousand dollars if you can manage it, then expand from there. What matters is establishing the habit of setting aside money before you spend it on other things. Keep this fund in a separate savings account, ideally one at a different bank or institution from where you do your regular banking.
Once you’ve built your emergency fund to a comfortable level, you can redirect some of those savings toward other goals like retirement accounts or debt repayment. Your emergency fund remains in place permanently because emergencies are a permanent feature of adult life.
4. Address High-Interest Debt Strategically
High-interest debt, particularly credit card balances, works directly against financial security because it creates an obligation that only grows larger. When you’re paying 15 to 25 percent interest annually on a balance, that debt compounds faster than most people can pay it down. This does not mean you need to eliminate all debt immediately, but it does mean prioritizing reduction of high-interest balances. Look at all your debts and identify which ones charge the highest interest rates. These deserve your immediate focus alongside making minimum payments on all other obligations.
You have several strategic approaches to tackling high-interest debt. Some people use the avalanche method, focusing extra payments on whichever debt charges the highest interest rate. Others prefer the snowball method, paying off the smallest balance first to gain quick psychological wins. Either approach works if you stay committed to it. While you’re working down high-interest debt, avoid accumulating new balances if possible. This sometimes means adjusting spending in other areas temporarily, which connects back to your realistic budget. As you eliminate high-interest debt, you free up money that was going toward interest payments, and you can redirect that toward other financial goals.
5. Start Saving for Retirement, Beginning Today
The single biggest factor affecting retirement security is time. The more years you have before retirement, the more time compound growth can work in your favor. If you’re in your twenties and feel retirement is distant, starting now with modest contributions accomplishes more than waiting until your forties to make larger contributions. This is because regular contributions, even small ones, have decades to grow through investment returns. If you’re starting later in life, do not let regret prevent you from starting, since beginning now is always better than not beginning at all.
Investigate the retirement options available to you. If your employer offers a retirement plan with a match, that match represents free money, and contributing at least enough to capture the full amount should be a priority. For self-employed individuals or those without employer plans, individual retirement accounts offer tax advantages that make regular contributions especially valuable. When navigating these decisions, professionals who need to align account selection with long-term tax strategy rely on a fiduciary financial advisor in Denver to ensure their contributions are structured in a way that genuinely serves their retirement goals.
The specific account type matters less than establishing the habit of contributing regularly. Even small contributions demonstrate commitment to your future and begin building the balance that will support you later. As your income grows or debt decreases, you can increase retirement contributions without major lifestyle disruption.
Conclusion
Creating a strong financial foundation does not require a large income, perfect timing, or years of financial expertise. It requires understanding where you stand, making intentional choices about spending and saving, and protecting yourself against unexpected events. The foundation rests on five main pillars: knowing your financial position, budgeting realistically, building an emergency fund, addressing high-interest debt, and saving consistently for retirement. At any age, these principles apply with equal importance. Your financial security grows from consistent choices made over time rather than dramatic actions taken once. Start where you are with the resources you have available today, and focus on steady progress. Small, disciplined actions repeated over months and years can create lasting financial stability and greater confidence in your future.